Digital Currencies 2026: 25% US CBDC Adoption?
Anúncios
By 2026, the United States could see a significant 25% adoption rate for its Central Bank Digital Currency (CBDC), fundamentally reshaping financial transactions and economic policy.
Anúncios
The financial landscape is constantly evolving, and a major shift is on the horizon: The Future of Digital Currencies in 2026: A 25% Increase in US CBDC Adoption? This isn’t just a theoretical discussion; it’s a critical examination of how central bank digital currencies (CBDCs) could redefine monetary systems, influence economic stability, and impact everyday financial activities for millions of Americans.
Anúncios
Understanding Central Bank Digital Currencies (CBDCs)
Central Bank Digital Currencies (CBDCs) represent a new frontier in financial innovation, distinct from existing digital payment systems or cryptocurrencies. They are digital forms of a country’s fiat currency, issued and backed by the central bank, offering a direct claim on the central bank itself. This fundamental difference provides a level of stability and trust that privately issued digital assets cannot match, positioning CBDCs as a potential cornerstone of future financial infrastructure.
Unlike commercial bank deposits, which are liabilities of private banks, a CBDC would be a direct liability of the Federal Reserve in the United States. This distinction is crucial for understanding its potential implications for financial stability and monetary policy. The design choices for a US CBDC, often referred to as a ‘digital dollar,’ are still under active discussion, encompassing various models from direct retail accounts to wholesale interbank systems.
Key Characteristics of CBDCs
CBDCs share several defining features that differentiate them within the broader digital asset ecosystem. These characteristics are central to their proposed benefits and potential challenges.
- Central Bank Backed: Issued and guaranteed by the central bank, ensuring stability and trust.
- Legal Tender Status: Expected to be recognized as legal tender, making them universally accepted for payments.
- Programmability: Potential for smart contract functionalities, allowing for automated payments and policy implementation.
- Privacy Considerations: Design choices will balance user privacy with regulatory needs and anti-money laundering (AML) efforts.
The introduction of a CBDC is not merely a technological upgrade but a profound policy decision with far-reaching consequences. It aims to enhance payment efficiency, foster financial inclusion, and maintain the stability of the monetary system in an increasingly digital world. The ongoing research and pilot programs globally underscore the seriousness with which central banks are approaching this innovation.
The Current Landscape of Digital Currencies in the US
The United States’ approach to digital currencies has been cautious but deliberate, reflecting the complexity and potential impact of such a monumental shift. While the Federal Reserve has been exploring the possibility of a digital dollar, it has emphasized that no decision has been made regarding its issuance. This careful stance contrasts with some other nations that are further along in their CBDC development or even launch phases.
Currently, the digital currency landscape in the US is dominated by private sector innovations. Cryptocurrencies like Bitcoin and Ethereum, stablecoins pegged to the US dollar, and traditional digital payment platforms (e.g., PayPal, Venmo) all play significant roles. These private solutions offer varying degrees of decentralization, stability, and utility, but none carry the full faith and credit of the US government.
The debate around a US CBDC often centers on how it would interact with these existing private digital payment systems. Proponents argue it could provide a more secure, efficient, and inclusive payment rail, while critics raise concerns about privacy, central bank overreach, and potential disruption to commercial banking. Understanding this complex interplay is essential for forecasting adoption rates.
Existing Digital Payment Systems
The US already boasts a robust array of digital payment options, which are deeply integrated into daily life. These systems have set a high bar for convenience and speed.
- Commercial Bank Apps: Offer instant transfers and bill payments.
- Third-Party Payment Processors: Facilitate online and mobile transactions for consumers and businesses.
- Stablecoins: Crypto assets pegged to the USD, used for faster, cheaper international transfers.
- Cryptocurrencies: Decentralized digital assets, primarily used for speculation and niche transactions.
The Federal Reserve’s research into a CBDC is partly driven by a desire to ensure the US dollar remains competitive in a global economy increasingly embracing digital assets. The potential benefits and risks are being rigorously evaluated through extensive public engagement and technical analysis, setting the stage for future policy decisions.
Projecting US CBDC Adoption: The 25% Threshold by 2026
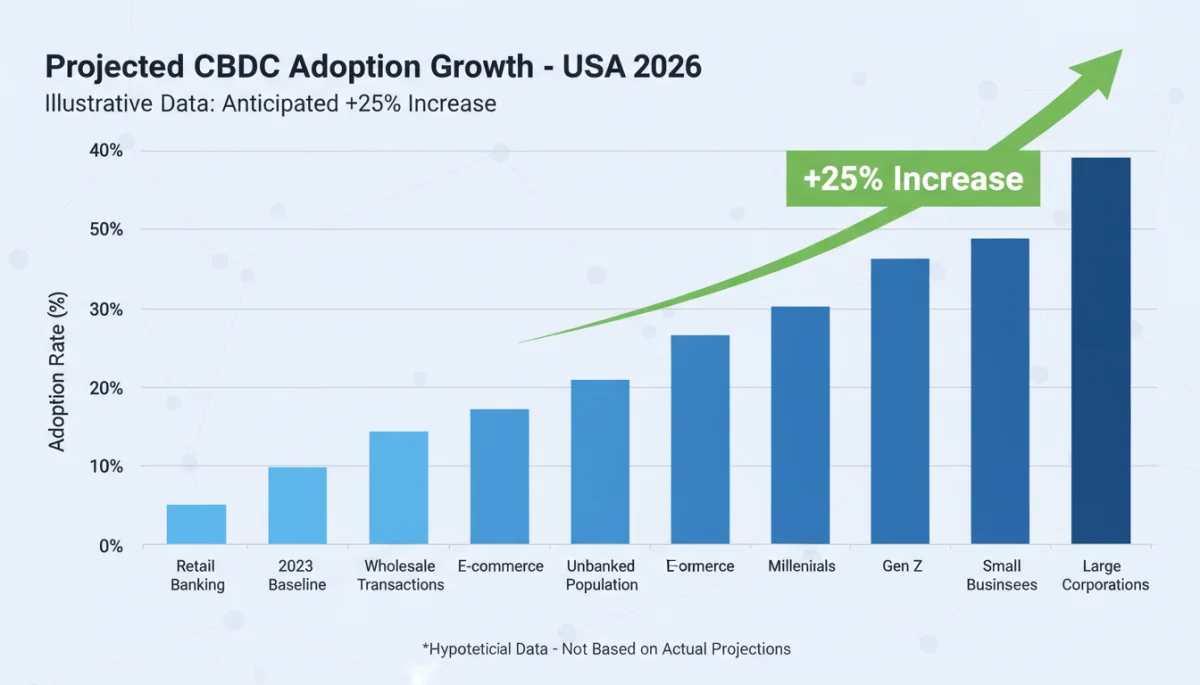
Forecasting a 25% adoption rate for a US CBDC by 2026 requires a nuanced understanding of economic, technological, and social factors. This projection assumes several critical developments, including the successful launch of a well-designed digital dollar, effective public education campaigns, and supportive regulatory frameworks. The path to widespread adoption is not without hurdles, but the potential advantages could drive significant uptake.
The 25% threshold suggests that a quarter of the US population, or a significant portion of its financial transactions, could be utilizing the digital dollar within a relatively short timeframe post-launch. This level of adoption would signal a substantial shift in payment preferences and financial behavior, impacting everything from retail transactions to international remittances.
Key drivers for this adoption could include improved payment efficiency, enhanced financial inclusion for the unbanked and underbanked, and increased security compared to certain existing payment methods. Furthermore, if a US CBDC offers unique features or incentives not available through private alternatives, it could accelerate its integration into daily financial routines. The speed of adoption will also depend heavily on how seamlessly it integrates with existing financial infrastructure and consumer habits.
Factors Influencing Adoption Speed
Several variables will play a crucial role in determining how quickly a US CBDC gains traction among the populace.
- Ease of Use: Intuitive interfaces and seamless integration with existing financial apps.
- Security Features: Robust protection against fraud and cyber threats.
- Privacy Guarantees: Clear policies that balance privacy with regulatory compliance.
- Incentives: Potential benefits like lower transaction fees or faster settlement times.
- Public Trust: Confidence in the central bank’s management and stability of the digital dollar.
Achieving a 25% adoption rate by 2026 would represent a significant milestone, indicating that the digital dollar has moved beyond experimental phases to become a recognizable and utilized component of the national financial system. This would have profound implications for both consumers and businesses.
Potential Benefits of US CBDC Adoption
The introduction and widespread adoption of a US CBDC could bring a host of benefits, addressing some long-standing challenges within the current financial system. These advantages extend across various sectors, from enhancing payment efficiency to bolstering financial stability and inclusion.
One of the primary benefits is the potential for more efficient and faster payment systems. A CBDC could enable near-instantaneous settlement of transactions, reducing the delays and costs associated with traditional payment rails. This would be particularly impactful for cross-border payments, where current systems can be slow and expensive, hindering international trade and remittances. For businesses, this means improved cash flow management and reduced operational costs.
Furthermore, a digital dollar could significantly advance financial inclusion. For the millions of unbanked and underbanked Americans, a CBDC could provide a low-cost, accessible, and secure way to participate in the formal financial system. This could open doors to essential financial services, fostering economic empowerment and reducing reliance on costly alternative financial products. The direct nature of a CBDC, bypassing commercial banks, could simplify access for those currently underserved.
Key Advantages for the Economy and Society
The broader societal and economic impacts of a CBDC could be transformative, offering solutions to current systemic inefficiencies.
- Enhanced Financial Inclusion: Providing accessible digital payment options for all citizens.
- Improved Payment Efficiency: Faster, cheaper, and more secure transactions.
- Monetary Policy Tools: New avenues for the central bank to implement and transmit monetary policy.
- Reduced Systemic Risk: A resilient payment infrastructure less susceptible to disruptions.
- International Competitiveness: Maintaining the dollar’s global standing in a digital age.
These potential benefits underscore why the Federal Reserve and other policymakers are seriously considering a US CBDC. The goal is to leverage technological advancements to create a more robust, equitable, and efficient financial system that serves all Americans.
Challenges and Risks Associated with CBDCs
While the potential benefits of a US CBDC are compelling, its implementation also presents significant challenges and risks that must be carefully addressed. These concerns range from privacy implications and cybersecurity vulnerabilities to potential impacts on the commercial banking sector and the broader financial ecosystem.
One of the most frequently cited concerns is privacy. A central bank-issued digital currency could potentially allow for unprecedented surveillance of financial transactions, raising questions about individual liberties and data protection. Striking the right balance between necessary regulatory oversight (e.g., anti-money laundering) and protecting user privacy will be a critical design challenge. Without robust privacy safeguards, public adoption could be severely hampered.
Cybersecurity is another paramount risk. As a direct liability of the central bank, a CBDC system would be a prime target for cyberattacks. The integrity and resilience of the digital dollar infrastructure would need to be exceptionally strong to prevent breaches, theft, or systemic disruptions. Any perceived vulnerability could erode public trust and undermine the entire initiative.
Major Obstacles to Overcome
Addressing these challenges will require careful planning, robust technological solutions, and comprehensive policy frameworks.
- Privacy Concerns: Balancing transparency with individual financial privacy.
- Cybersecurity Threats: Protecting against sophisticated attacks on critical infrastructure.
- Disintermediation Risk: Potential impact on commercial banks and their role in the financial system.
- Technological Complexity: Designing and implementing a secure, scalable, and resilient system.
- Public Acceptance: Overcoming skepticism and building widespread trust.
Navigating these complex risks effectively will be crucial for the successful rollout and adoption of a US CBDC. Policymakers must engage in thorough public discourse and technical evaluations to build a system that is both beneficial and secure for all users.
The Global Context: CBDC Developments Worldwide
The United States is not operating in a vacuum when it comes to CBDCs; a global race is underway, with numerous countries actively exploring, piloting, or even launching their own digital currencies. Understanding this international landscape provides valuable context for the US’s position and the pressures that might accelerate its own CBDC development.
Many central banks, particularly in emerging economies, see CBDCs as a way to improve financial inclusion, modernize payment systems, and reduce the cost of remittances. Countries like the Bahamas have already launched their Sand Dollar, providing a live case study for retail CBDC implementation. China’s digital yuan (e-CNY) project is perhaps the most prominent, with large-scale pilot programs involving millions of users and extensive merchant adoption, offering insights into both the potential and challenges of a major economy’s CBDC.
European nations are also heavily invested, with the European Central Bank (ECB) actively researching a digital euro, focusing on privacy, resilience, and its role in a sovereign European payment system. These global developments highlight the growing recognition that digital currencies are an inevitable evolution of money, pushing nations to adapt or risk falling behind in the global financial arena.
International CBDC Initiatives
A diverse range of approaches and motivations characterizes the global CBDC movement.
- Bahamas (Sand Dollar): Full retail launch, focused on financial inclusion and resilience.
- China (e-CNY): Extensive pilot program, aiming for domestic payment efficiency and international use.
- European Central Bank (Digital Euro): Research phase, emphasizing privacy and sovereignty.
- Sweden (e-krona): Pilot program, exploring a cashless society’s digital currency needs.
- India (Digital Rupee): Wholesale and retail pilots, aiming for payment system modernization.
The experiences of these countries provide critical lessons and best practices for the US as it continues its own exploration. The global momentum behind CBDCs suggests that regardless of the US’s specific timeline, digital forms of central bank money are poised to play an increasingly important role in the future of finance worldwide.
| Key Aspect | Brief Description |
|---|---|
| CBDC Definition | Digital form of national fiat currency, issued and backed by the central bank. |
| 2026 Adoption Goal | Projected 25% increase in US CBDC adoption, indicating significant integration. |
| Key Benefits | Enhanced payment efficiency, financial inclusion, and new monetary policy tools. |
| Major Challenges | Privacy concerns, cybersecurity risks, and potential impact on commercial banking. |
Frequently Asked Questions About US CBDC Adoption
A CBDC is a digital form of a country’s fiat currency, issued and backed by its central bank. Unlike cryptocurrencies, it is centralized and aims to complement physical cash and existing digital payments, offering stability and direct claims on the central bank.
The US is exploring a CBDC to enhance payment efficiency, promote financial inclusion, maintain the dollar’s international standing, and provide a secure digital payment option. It also seeks to address risks associated with private digital currencies.
A US CBDC would be centralized and issued by the Federal Reserve, making it a stable, government-backed asset. Cryptocurrencies are typically decentralized, privately issued, and often subject to high price volatility, lacking central bank backing.
Primary concerns include privacy implications for users, the potential for cybersecurity vulnerabilities, the impact on commercial banks, and the sheer technological complexity of implementation. Public trust and acceptance are also significant hurdles.
Achieving 25% adoption by 2026 is ambitious but feasible if a well-designed CBDC is launched soon, accompanied by strong public education and integration with existing financial systems. Incentives and perceived benefits would also play a crucial role.
Conclusion
The prospect of a 25% increase in US CBDC adoption by 2026 is more than a mere statistic; it represents a potential paradigm shift in how Americans manage their money and interact with the financial system. While the journey to a digital dollar is fraught with complex challenges, from privacy concerns to cybersecurity risks, the potential benefits in terms of efficiency, inclusion, and monetary stability are substantial. As global central banks continue their digital currency endeavors, the United States remains at a critical juncture, poised to make decisions that will shape its financial future for decades to come. The path forward demands careful consideration, robust innovation, and an unwavering commitment to public trust and security.
