Credit Card Fraud Alerts Surge 15% in Q4 2025: FBI Report
Anúncios
The FBI’s Q4 2025 report indicates a 15% surge in credit card fraud alerts, detailing new scams impacting U.S. consumers.
Anúncios
The landscape of financial security is constantly evolving, and recent data paints a concerning picture for consumers across the United States. A new FBI report has revealed a significant 15% surge in credit card fraud alerts during the fourth quarter of 2025, highlighting an urgent need for vigilance and proactive protection against increasingly sophisticated scams. This alarming trend suggests that fraudsters are developing more cunning methods to target unsuspecting individuals, making it imperative for everyone to stay informed and take necessary precautions.
Anúncios
Understanding the Q4 2025 Fraud Surge
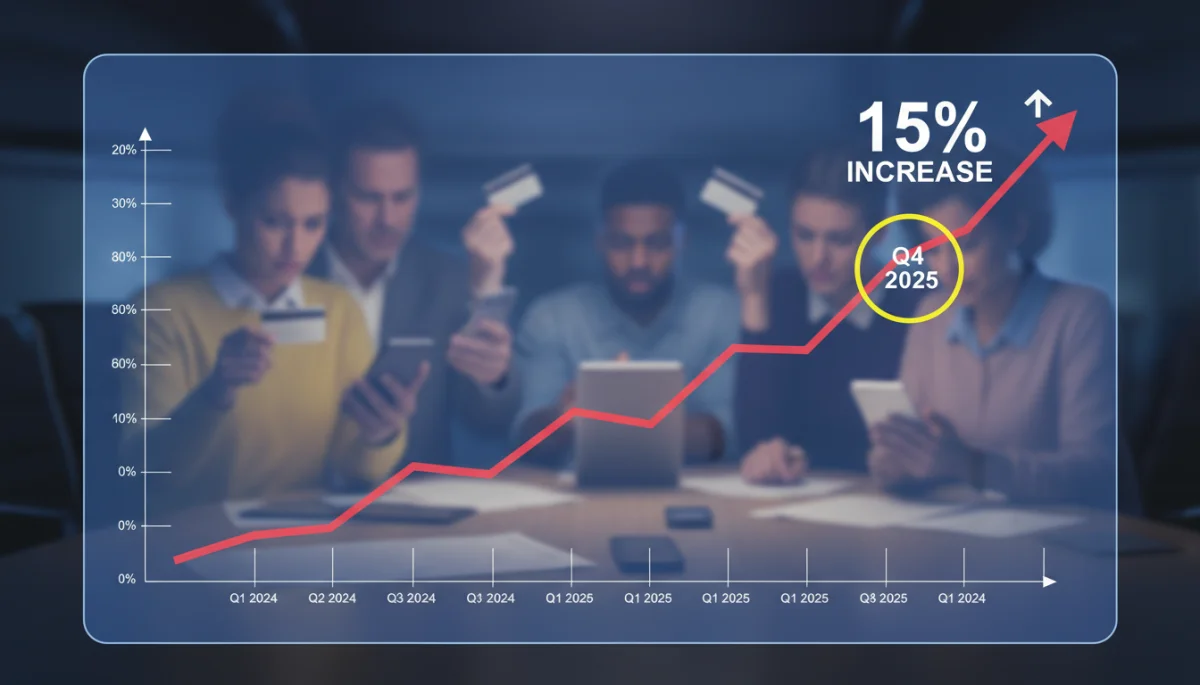
The FBI’s latest report on financial crimes has brought to light a substantial increase in credit card fraud alerts, signaling a critical period for consumer awareness. This 15% rise in Q4 2025 is not just a statistic; it represents a tangible threat to the financial well-being of millions of Americans. The report meticulously details how these fraudulent activities are evolving, moving beyond traditional methods to embrace more sophisticated digital and social engineering tactics. Understanding the scope and nature of this surge is the first step in building a robust defense against it.
The fourth quarter traditionally sees an uptick in consumer spending due to holiday seasons, which unfortunately also creates a fertile ground for fraudsters. However, the magnitude of this year’s increase suggests more than just seasonal opportunism; it points to a strategic shift in how scams are executed. From compromised online retailers to elaborate phishing schemes, the avenues for fraud are expanding, requiring consumers to be more cautious than ever before. This section will delve into the underlying causes and initial impacts of this worrying trend.
Key Factors Contributing to the Surge
- Increased Online Shopping Vulnerabilities: The continued growth of e-commerce has opened more doors for data breaches and insecure transaction points.
- Sophisticated Phishing and Smishing Attacks: Scammers are using highly personalized emails and text messages to trick consumers into revealing sensitive information.
- Rise of AI-Powered Scams: Artificial intelligence is being leveraged to create more convincing fake websites, voice impersonations, and deepfake videos.
- Data Breaches from Third-Party Vendors: Many fraud incidents stem from breaches in less secure third-party payment processors or service providers.
The FBI report emphasizes that many of these factors are interconnected, creating a complex web of vulnerabilities. Consumers often fall victim due to a combination of exposure to compromised data and sophisticated psychological manipulation. This intricate interplay makes it challenging for individuals to identify and avoid scams, underscoring the need for continuous education and updated security practices. The overall conclusion is that while technology offers convenience, it also presents new battlegrounds for financial security.
New Scams Targeting U.S. Consumers: What to Watch For
The FBI report does more than just highlight the increase in fraud; it provides a crucial breakdown of the novel scam tactics that are gaining traction. These new methods are designed to bypass traditional security measures and exploit human vulnerabilities, making them particularly dangerous. Consumers must familiarize themselves with these emerging threats to effectively protect their personal and financial information. The days of easily identifiable scam emails are largely over; today’s fraudsters are masters of disguise.
One prominent new scam involves sophisticated social engineering techniques, where fraudsters impersonate trusted entities like banks, government agencies, or even close family members. They often create a sense of urgency or fear, pressuring victims into making quick decisions that compromise their accounts. Another emerging trend is the use of QR code scams, where malicious codes are placed in public spaces or sent via email, redirecting users to fake websites designed to steal credentials. These methods are insidious because they leverage everyday technologies that people trust.
Beyond these, there’s a growing concern around synthetic identity fraud, where criminals combine real and fake information to create entirely new identities, which are then used to open credit accounts. This type of fraud is particularly difficult to detect because it doesn’t directly involve stealing an existing identity but rather creating a new one from scratch. The report also touches upon the dark web’s role in facilitating these crimes, with stolen data and sophisticated hacking tools readily available to those with malicious intent. Remaining vigilant and skeptical of unsolicited communications is more important than ever.
Impact on Financial Institutions and Consumer Trust
The surge in credit card fraud alerts has far-reaching consequences, extending beyond individual financial loss to impact the broader financial ecosystem. Financial institutions are grappling with increased operational costs associated with fraud detection, investigation, and recovery. This includes investing in more advanced AI-driven security systems, hiring additional fraud analysts, and dealing with the administrative burden of processing a higher volume of disputed transactions. The financial strain can be significant, potentially leading to higher fees or reduced services for legitimate customers.
Perhaps even more damaging is the erosion of consumer trust. When individuals fall victim to fraud, their confidence in the security of their financial institutions can be severely shaken. This lack of trust can lead to reduced engagement with digital banking services, a reluctance to use credit cards online, and an overall sense of anxiety about personal financial security. Rebuilding this trust requires transparent communication from banks, efficient resolution of fraud cases, and continuous efforts to enhance security protocols. The FBI report underscores the necessity for a collaborative approach between consumers and financial entities to combat this growing threat effectively.
Challenges Faced by Banks
- Balancing Security with User Experience: Implementing stringent security measures without hindering legitimate transactions is a constant struggle.
- Rapidly Evolving Fraud Tactics: Staying ahead of fraudsters who constantly innovate their methods requires continuous adaptation and investment.
- Customer Education Burden: Financial institutions bear a significant responsibility in educating their customers about new threats and safe practices.
- Regulatory Compliance: Adhering to evolving data protection and fraud prevention regulations adds another layer of complexity.
The report highlights that the battle against credit card fraud is a perpetual arms race. As financial institutions deploy new defenses, fraudsters develop new attacks. This dynamic requires not just reactive measures but also proactive strategies that anticipate future threats. Ultimately, the success of this fight hinges on robust security infrastructure, informed consumers, and effective collaboration across the financial industry to maintain stability and trust.
Protecting Yourself: Essential Consumer Strategies
In the face of rising credit card fraud, consumers are not powerless. There are several proactive strategies individuals can employ to significantly reduce their risk of becoming a victim. The FBI report itself emphasizes consumer responsibility as a critical component of a comprehensive fraud prevention strategy. Implementing these measures can create a strong personal defense against even the most sophisticated scams, ensuring your financial well-being remains intact.
One of the most fundamental steps is regularly monitoring your credit card statements and credit reports. Discrepancies, no matter how small, should be investigated immediately. Many financial institutions offer fraud alert services that notify you of suspicious activity, and enrolling in these services is highly recommended. Setting up multifactor authentication (MFA) on all financial accounts adds an extra layer of security, making it much harder for unauthorized users to gain access even if they have your password. Strong, unique passwords for all online accounts are also non-negotiable in today’s digital landscape.
Key Prevention Tips
- Enable Fraud Alerts: Sign up for text or email alerts from your bank for all transactions.
- Use Strong, Unique Passwords: Avoid reusing passwords across different platforms and use a password manager.
- Be Wary of Unsolicited Communications: Always verify the sender of emails, texts, or calls requesting personal information.
- Review Statements Regularly: Check credit card and bank statements for unauthorized charges at least once a week.
Furthermore, exercising caution when using public Wi-Fi networks for financial transactions is crucial, as these networks are often insecure and vulnerable to eavesdropping. Using a Virtual Private Network (VPN) can provide an added layer of protection in such scenarios. Finally, staying informed about the latest scam tactics, as detailed in reports like the FBI’s, empowers you to recognize and avoid new threats before they can cause harm. Education and vigilance are your most powerful tools against fraud.
The Role of Technology in Fraud Detection and Prevention
Technology plays a dual role in the current fraud landscape: it enables new forms of attack, but it also provides powerful tools for defense. Financial institutions and cybersecurity firms are continually developing and deploying advanced technological solutions to detect and prevent credit card fraud. These innovations are critical in the ongoing battle against increasingly sophisticated criminal enterprises, offering a glimmer of hope in an otherwise challenging environment. The FBI report specifically points to the advancements in AI and machine learning as game-changers.
Artificial intelligence and machine learning algorithms are now central to fraud detection systems. These technologies can analyze vast amounts of transaction data in real-time, identifying patterns and anomalies that human analysts might miss. By learning from past fraudulent activities, AI can predict and flag suspicious transactions, often before they are completed. This proactive approach significantly reduces the window of opportunity for fraudsters and minimizes potential losses. Behavioral biometrics, which analyze unique user interactions with devices, are also gaining traction as a way to verify identity and detect account takeovers.
Beyond AI, encryption technologies are becoming more robust, protecting sensitive data both in transit and at rest. Tokenization, where credit card numbers are replaced with unique, randomly generated tokens for transactions, adds another layer of security, making stolen data useless to fraudsters. Mobile payment platforms also integrate advanced security features, such as fingerprint or facial recognition, providing secure alternatives to traditional card payments. While no technology is foolproof, the continuous advancement of these tools is essential in bolstering our collective defenses against financial crime and protecting consumers from the rising tide of fraud.
Future Outlook: Trends and Predictions for 2026 and Beyond
Looking ahead, the fight against credit card fraud is expected to continue evolving, with new challenges and opportunities emerging. The FBI report’s Q4 2025 findings serve as a stark reminder that vigilance cannot waver. As technology advances, so too will the methods employed by fraudsters, necessitating a dynamic and adaptive approach from both consumers and financial institutions. Understanding these future trends can help prepare us for what lies ahead and formulate more effective long-term prevention strategies.
One major prediction for 2026 and beyond is the increasing sophistication of AI-powered scams. Deepfakes, which can convincingly mimic voices and video, are likely to become more prevalent in impersonation scams, making it even harder for individuals to discern authenticity. The proliferation of IoT (Internet of Things) devices also presents new vectors for attack, as unsecured devices could become gateways for criminals to access personal networks and data. This expansion of attack surfaces means that cybersecurity will need to become an even more integrated part of daily life.
Anticipated Challenges and Solutions
- Quantum Computing Threats: The long-term threat of quantum computing breaking current encryption standards will necessitate the development of quantum-resistant cryptography.
- Cross-Border Fraud Syndicates: International collaboration will be crucial to combat global fraud networks that operate across jurisdictions.
- Enhanced Biometric Security: Wider adoption of advanced biometric authentication methods will be needed to secure transactions.
- Personalized Consumer Education: Tailored educational programs will help consumers understand specific threats relevant to their online behavior.
Furthermore, regulatory bodies are expected to introduce more stringent data protection and fraud prevention laws, placing greater responsibility on companies to secure consumer data. Collaboration between law enforcement, financial institutions, and tech companies will be paramount in sharing threat intelligence and developing coordinated responses. Ultimately, the future of financial security will depend on a collective commitment to innovation, education, and proactive defense against the ever-present threat of credit card fraud. The lessons from the Q4 2025 surge will undoubtedly shape these future strategies.
| Key Point | Brief Description |
|---|---|
| Fraud Surge in Q4 2025 | FBI report indicates a 15% increase in credit card fraud alerts, impacting U.S. consumers significantly. |
| Evolving Scam Tactics | New methods include advanced social engineering, QR code scams, and synthetic identity fraud. |
| Consumer Protection | Regular monitoring, strong passwords, MFA, and vigilance are crucial for personal security. |
| Technological Defense | AI, machine learning, and encryption are vital tools in detecting and preventing fraud. |
Frequently Asked Questions About Credit Card Fraud
The surge is attributed to increased online shopping vulnerabilities, more sophisticated phishing and smishing attacks, the rise of AI-powered scams, and data breaches from third-party vendors, as detailed in the latest FBI report.
New scams include advanced social engineering tactics, malicious QR code scams, and synthetic identity fraud where criminals create new identities using a mix of real and fake information to open credit accounts.
Essential strategies include regularly monitoring statements and credit reports, enabling fraud alerts, using strong and unique passwords, activating multifactor authentication, and being cautious of unsolicited communications.
Financial institutions are investing in AI-driven security systems, hiring fraud analysts, and educating customers. They are also developing advanced technologies like real-time transaction monitoring and tokenization to protect accounts.
Experts predict continued evolution of AI-powered deepfake scams and new threats from IoT devices. Future prevention will require quantum-resistant cryptography, international collaboration, and enhanced biometric security measures.
Conclusion
The FBI’s report detailing a 15% surge in credit card fraud alerts in Q4 2025 serves as a stark warning and a critical call to action for U.S. consumers and financial institutions alike. The evolving nature of these scams, from sophisticated social engineering to AI-powered impersonations, demands an equally dynamic response. While technological advancements offer powerful tools for detection and prevention, the ultimate defense lies in informed and vigilant consumers. By adopting proactive security measures, staying educated on emerging threats, and fostering a collaborative environment between individuals and financial entities, we can collectively build a more resilient financial ecosystem against the persistent challenge of credit card fraud.
